Eight Questions to Ask Any Private Credit Manager, Part 2 of 5
August 26, 2026 |
Real estate advisors of accredited investors are not looking for another salesperson. They are looking for investment partners who understand their fiduciary responsibilities, their due-diligence process, and their obligation to their clients. In that spirit, here are the eight questions I believe every advisor should ask any private real estate credit manager—including us.
- Where does your deal flow come from? A lender with limited deal flow may feel pressure to deploy capital into whatever is available. Ask how many opportunities the manager reviews for every loan it makes.
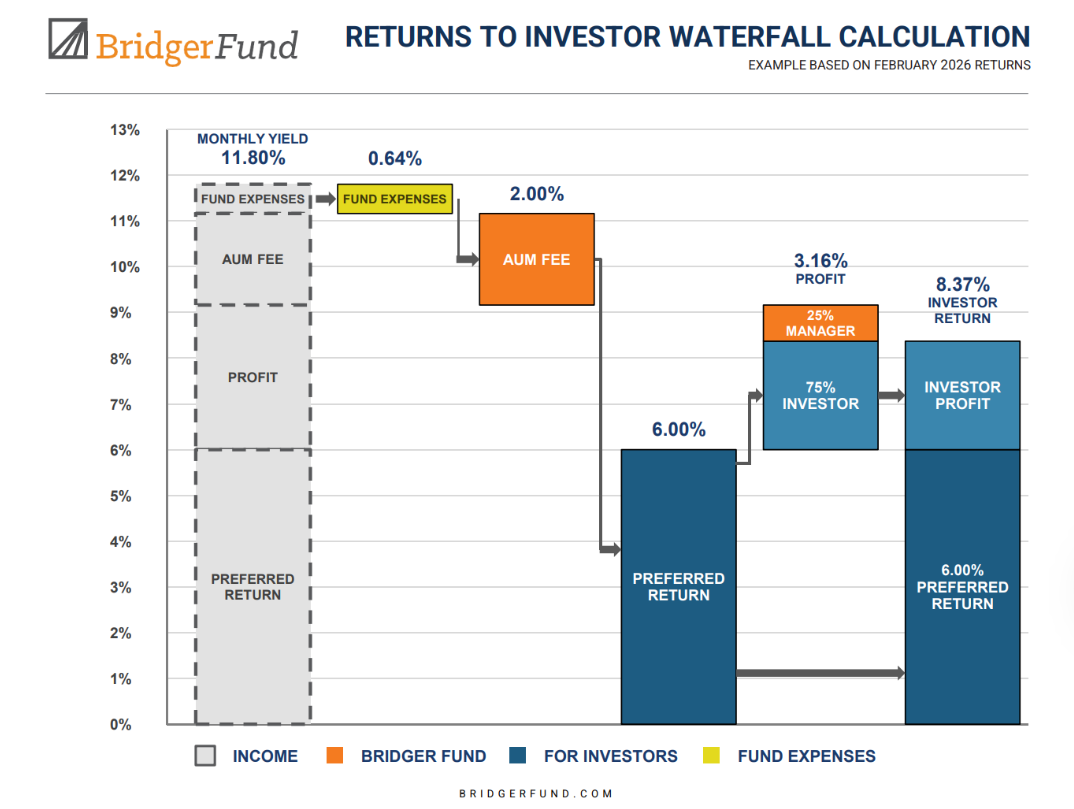
- What is behind the yield? Understand the full economics: origination fees, rate, fund expenses, management fees, and the distribution waterfall. Our CFO has published a tier-by-tier breakdown using actual monthly numbers.
- How disciplined is the underwriting? What is the weighted average loan-to-value? What is the ceiling? What will the manager not touch? Vague answers here are a red flag.
- Am I buying a portfolio or a handful of transactions? A single-loan syndication concentrates exposure in one property, one borrower, and one exit. The Bridger Fund currently holds33 loans, with the average loan amount of $1.5 million.
- How long is my capital committed—and how does liquidity actually work? Many private real estate vehicles require 24–36 month lockups or longer. Bridger’s initial 12-month lockup, followed by a defined redemption process, is set out in our governing documents—and we have published a plain-English explanation of exactly where redemption cash comes from.
- Who makes the lending decisions? How many people approve each loan? Is approval unanimous? Do the decision-makers invest alongside you? Every Bridger loan requires unanimous approval from our investment committee, who also represent investors.
- What happens when a loan underperforms? Every lender will eventually face a loan that requires attention. Ask for the process—in writing—before you invest. I address this directly in Part 4 of this series.
- What will communication look like after I wire funds? Monthly reporting? Portfolio-level transparency? Direct access to decision-makers? The answer should be specific, and the manager should be held to it.
Two managers can offer the same headline yield and represent very different risks. The questions above are how sophisticated capital tells them apart. At Bridger Fund, we welcome every one of them—and we believe the willingness to answer them specifically is itself a differentiator.